China's humanoid gold rush hits the wall: star startups' old shares can't sell even at half price
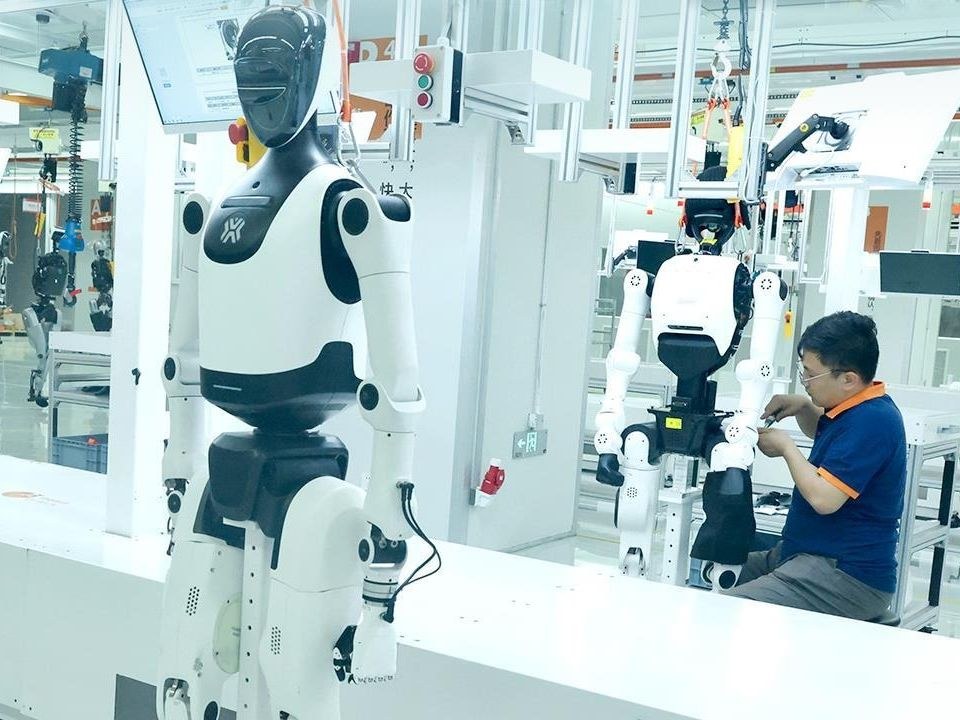
With listings stalled and valuations built on shaky revenue, early investors are discovering the market's real price.
A year ago, shares in China's leading humanoid robot startups were fought over at dizzying valuations. Now one early investor is trying to offload his stake in an embodied-AI startup — bought at a 3-billion-yuan post-money valuation early this year, when the company now quotes itself at 22 billion yuan — at roughly half the company's asking price, about 12 billion yuan. No takers. The episode, documented in a Rongzhong Finance investigation published October 19, captures a market that has swung from scramble to stalemate in under a year.
The reversal is stark. Last August, fund stakes in top humanoid companies changed hands at implied valuations near 39 billion yuan; AgiBot stakes traded around 25 billion. At a private-equity liquidity summit in January, buyers lined up with 30-to-50-million-yuan tickets for humanoid and commercial-space secondary shares. Then the music stopped. In July, about 34 embodied-AI companies raised roughly 12 billion yuan — down nearly 30 percent from June's 17.8 billion. After Unitree's listing, its stock slid steadily; institutions turned bearish internally; one placement agent said his firm had stopped taking on new embodied-AI mandates altogether.
The trigger was regulatory. In early September, The Information reported that securities regulators had informally told banks and investment firms that humanoid robot companies seeking listings must demonstrate recurring revenue, narrowing losses or genuinely significant technology. Cailian Press's follow-up added texture: revenue must be sustained, real and replicable — not propped up by subsidies, related-party deals, one-off gains or data-center income; losses must keep narrowing; shipments must scale; customers must be stable. Some brokerages deny receiving formal guidance, describing it instead as tightened sponsor review. Either way, the market's verdict was unanimous: more than 20 core humanoid companies are in IPO coaching, filing or issuance, 46 robotics-related firms are queued for Hong Kong listings — and the exit door just got narrower.
The bifurcation is now on public display. On October 13, Stardust Intelligence announced a 1-billion-yuan raise at a 15-billion-yuan valuation, led by a Shenzhen Capital Group-affiliated investor with existing shareholders following on. On October 19, Yinghe Robotics held its first creditors' meeting at the Shenzhen Intermediate People's Court — the inventory to be tallied included auction-failed equipment, frozen subsidiary equity, and years of unpaid supplier bills and wages. As Huaxin Capital partner Liang Dongjian put it: the liquidation has begun, but the tide has not gone out — the water is being redistributed, the head is still rising while the tail is beached.
Secondary shares are where real price discovery happens. New rounds can be sustained by fresh money; old stakes can only wait for a willing buyer. One Shenzhen embodied company valued at 4 billion yuan planned its next round at 8 billion but ended up bundling old shares with new stock, landing the effective valuation near 6 billion. Reuters cited one investor's estimate that stripping data-center-related revenue out of some companies could cut valuations by 60 to 70 percent. Some firms now reportedly delay share reform to restrict old-share outflows. For those who bought at mid-year peaks — Zhifang went from 10 to 20 billion yuan in 126 days, Qianxun Intelligence in 33 — the pain is only starting. Many companies still sit on earlier funding; the real financing crunch, several investors warn, may concentrate after November.